Hyperlocal micromarkets redefine housing
The article explains how housing data is shifting from broad geographic averages to hyperlocal micromarkets like subdivisions and buildings, which better
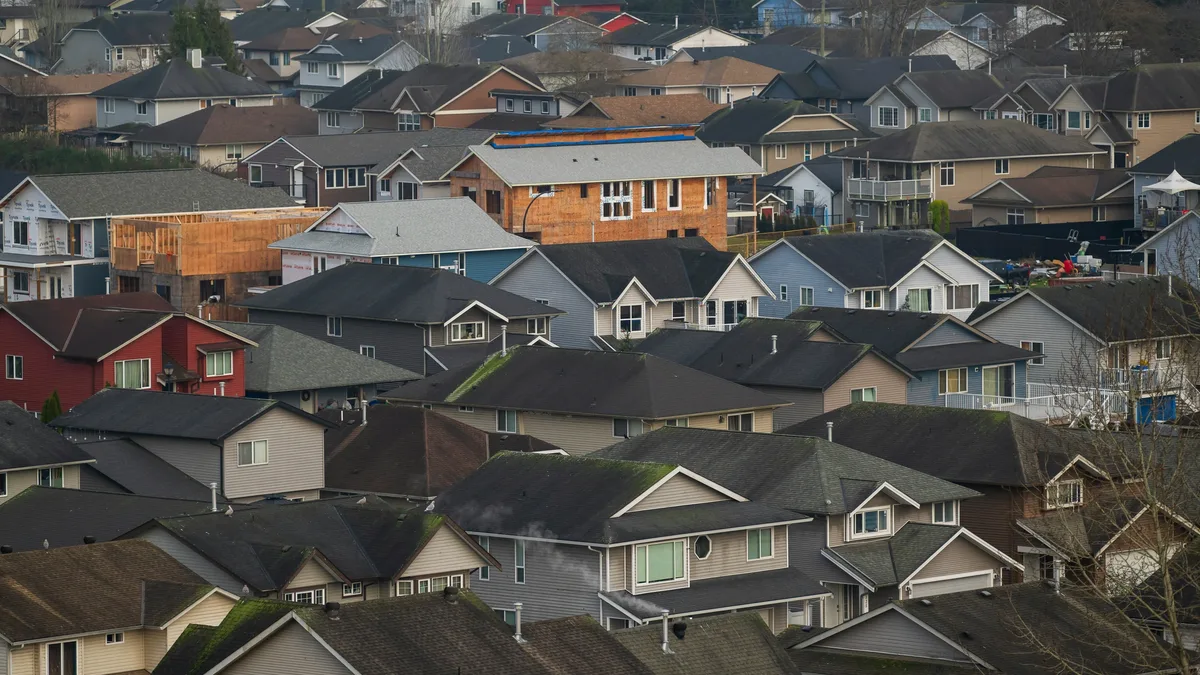
Real estate professionals have long relied on ZIP codes and neighborhood statistics to understand housing markets, but these broad measures often fail to capture the true competitive environment for individual properties. A property’s actual market may differ significantly from its geographic surroundings due to buyer preferences, building characteristics, and localized competition.
ZIP codes were created by the U.S. Postal Service for mail efficiency, not to define housing markets. While they help aggregate data and compare broad conditions, they can encompass multiple distinct housing environments. Similarly, neighborhoods offer more context but still do not always align with where a property’s real demand and competition come from.
Fannie Mae and Freddie Mac now explicitly distinguish between a neighborhood and a property’s market area. Their definition focuses on where demand originates and where most competition is located. They note that even side-by-side properties can have different market areas if they appeal to different buyer segments, highlighting that market relevance depends on substitution patterns, not only proximity.
Attempting to improve market resolution by simply shrinking the geographic radius around a property is misleading. For example, two units in the same high-rise condo building may differ in floor, view, layout, or ownership costs, leading buyers to treat them as non-competitive. Conversely, a buyer might consider units in nearby competing buildings, meaning the relevant market can be both narrower in property similarity and broader in geographic scope.
This complexity is why housing researchers use the term "micromarket" to describe concentrated segments-such as subdivisions, developments, or individual buildings-where meaningful substitution relationships exist. These micromarkets reflect not only location but also property characteristics, price, quality, and buyer preferences.
While property records are abundant, turning them into useful hyperlocal insights requires more than data collection. Fields like RESO’s Data Dictionary standardize entries such as ‘SubdivisionName’ as strings, but standardization does not ensure semantic clarity. Questions remain: Are ‘Palm Beach Towers’ and ‘Palm Beach Tower’ the same? Do phases of a subdivision count as one market? Which nearby communities truly compete? Answering these requires entity resolution, normalization, classification, and modeling of relationships between properties and competitive alternatives.
The rise of AI increases the urgency of solving this problem. AI can process thousands of records quickly, generate summaries, and detect patterns far faster than human review. However, if the underlying data includes properties that do not actually compete, the analysis-no matter how sophisticated-will be flawed. As one 2025 study in EPJ Data Science showed, market structure can be inferred from listing relationships using network methods, offering a path beyond predefined boundaries.
The housing industry is also undergoing a data shift on the appraisal side. UAD 3.6 entered broad production in January 2026, and as of November 2, 2026, all new appraisal reports submitted through UCDP must use this version. Fannie Mae describes the update as part of a move toward more flexible, dynamic, and machine-readable appraisal reporting.
While UAD 3.6 does not resolve micromarket definition, it signals a broader trend toward richer, structured property data. The next challenge is not only describing individual properties but mapping how they relate to one another in competitive markets.
City, ZIP code, and neighborhood data will remain useful for understanding general housing trends. But for decisions about buying, selling, or appraising a specific home, professionals need to know: What recent sales truly matter? What competes with this property now? Which homes would a similar buyer realistically consider? What has changed in this specific residential context?
As Jake Miakota, CEO of Subdivisions.com, observes, the next useful layer of housing data may finally help answer the core question: What does this property belong with? Because while real estate is local, the market that matters for one home often begins where general locality ends.